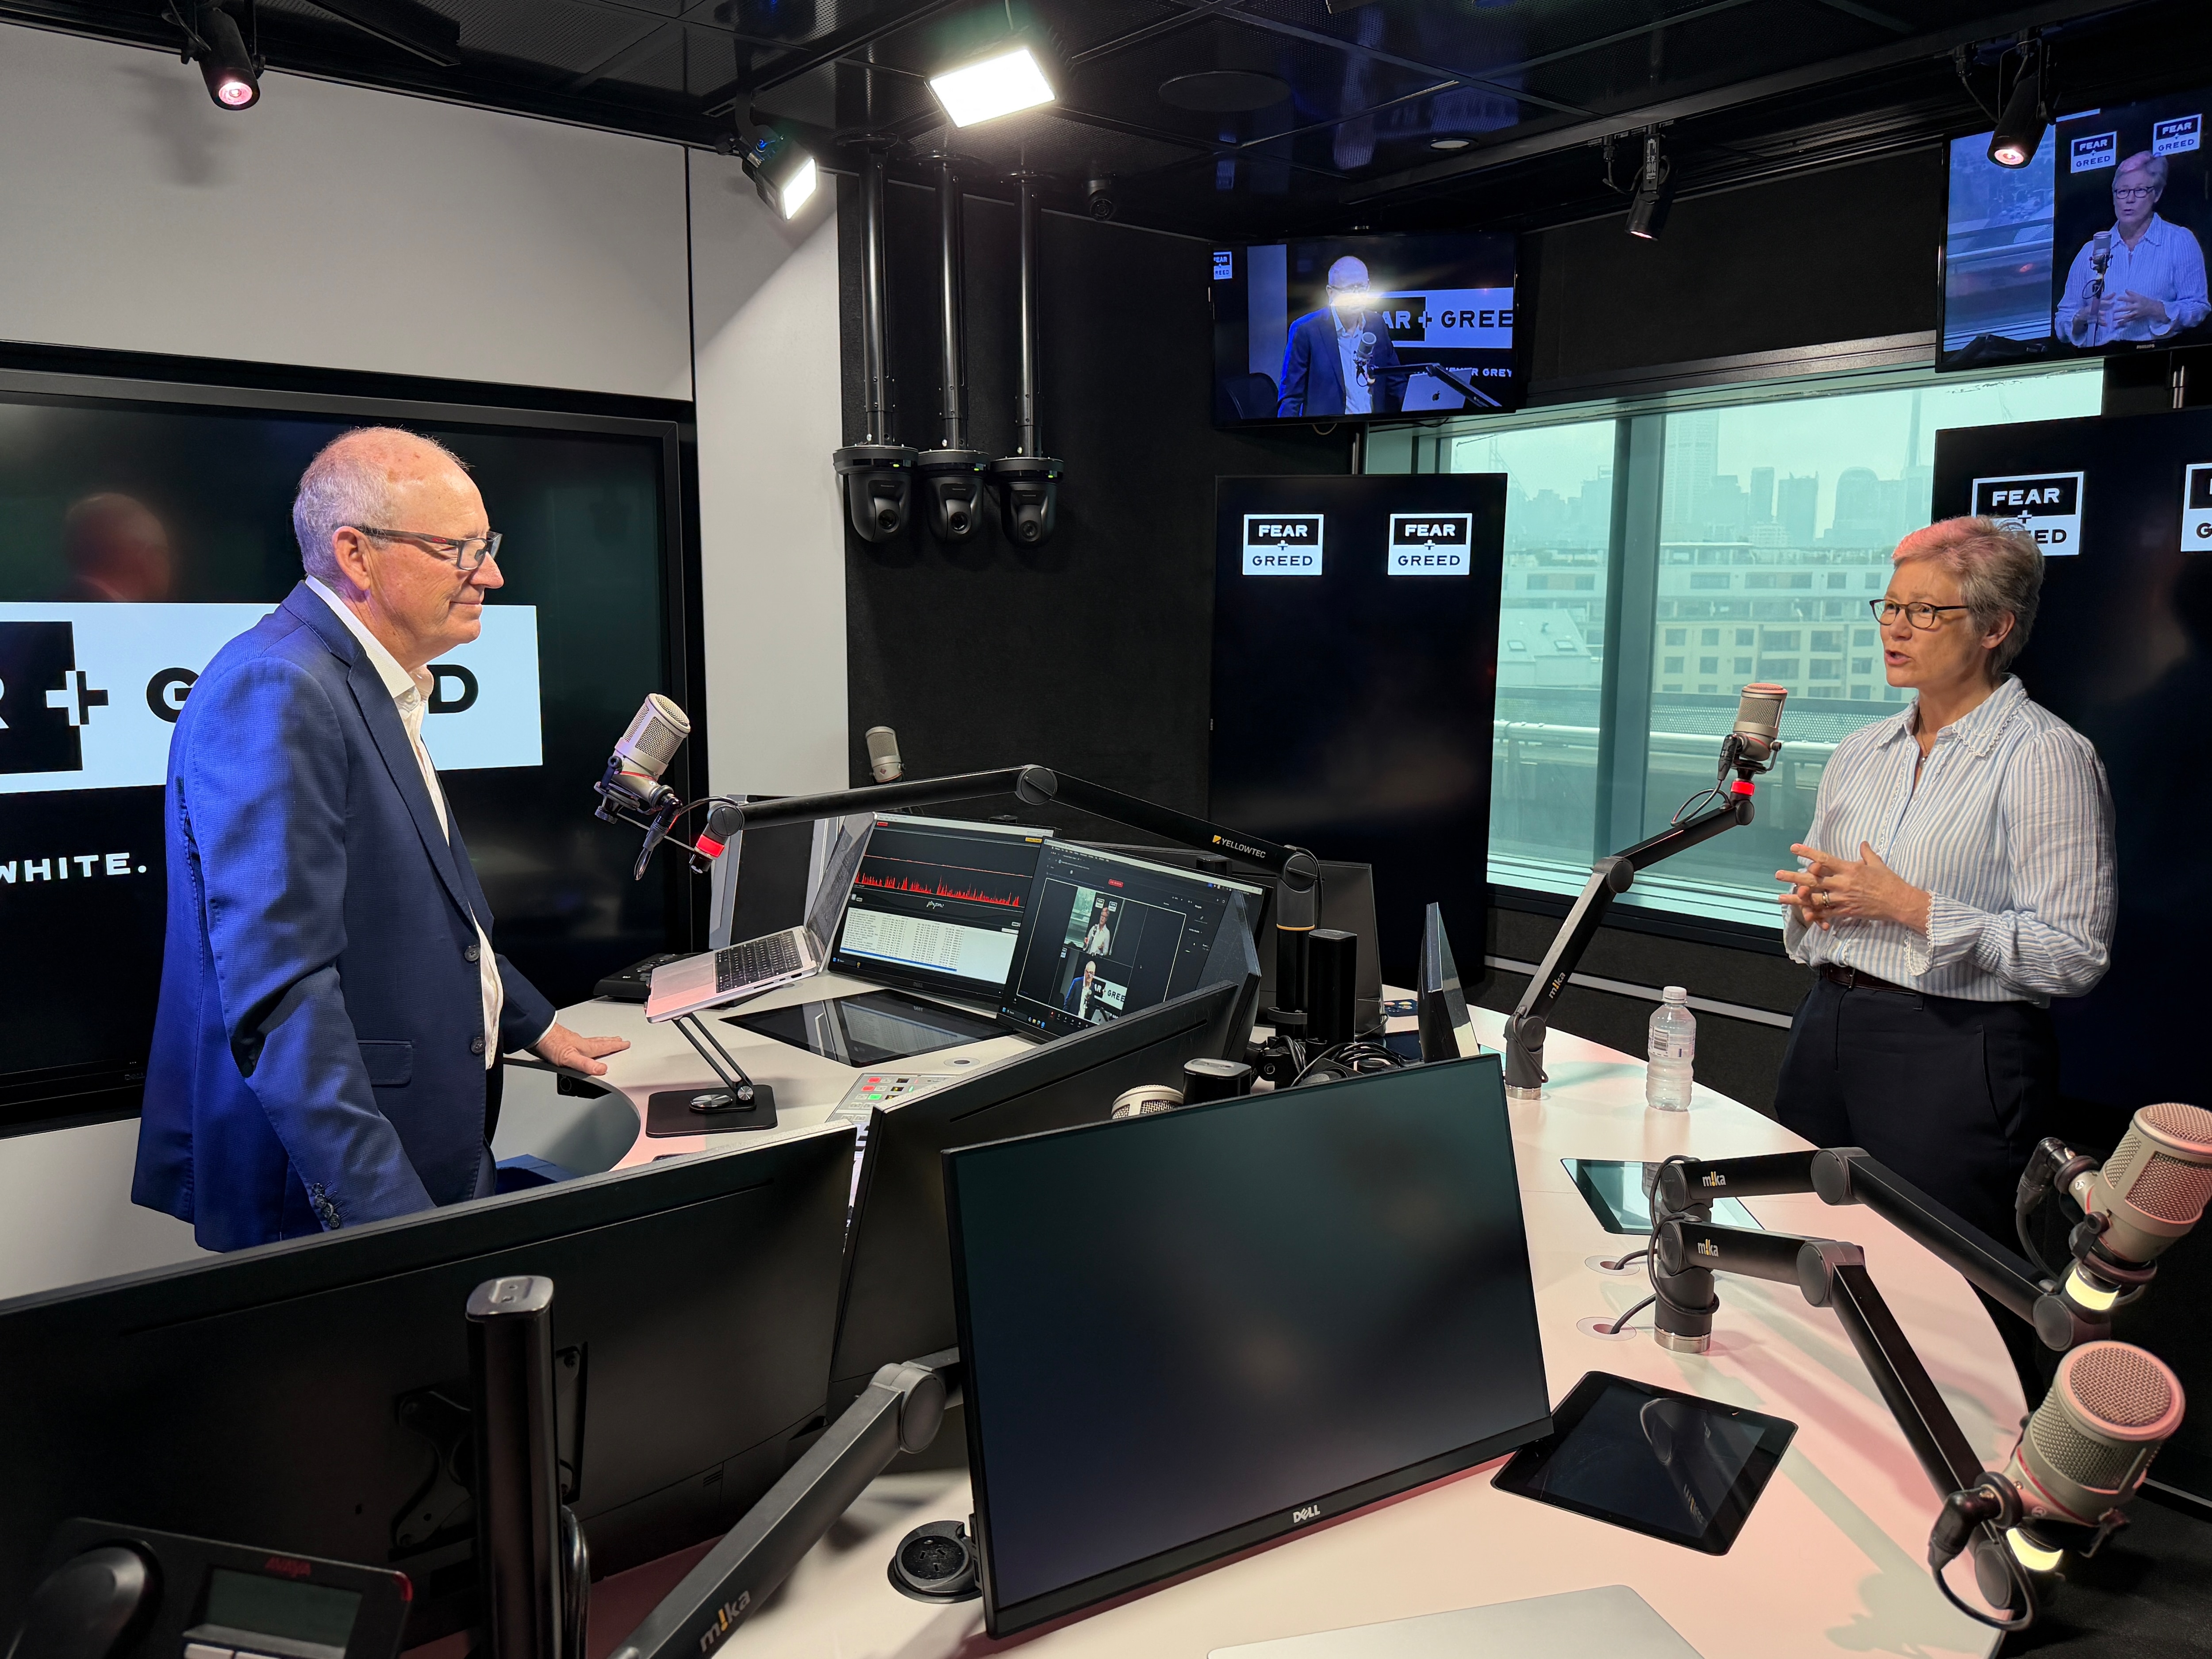
NAB Chief Economist Sally Auld this morning joined the first episode of The Week Ahead with NAB, a new weekly segment on the Fear & Greed Q&A podcast that explores the economic events, data releases and market developments shaping the week ahead.
NAB RBA Watch: RBA hikes by 25bps as expected - NAB

30th September 2026
Economy & Markets
Outcome and Assessment
In a unanimous decision, the RBA increased the cash rate by 25bps as expected by markets and the consensus of economists alike. The final paragraph of the Statement notes that “The Board will continue to do what it considers necessary to bring inflation sustainably back to target, including increasing the cash rate target further if needed.”
The main drivers of the decision were essentially two-fold. First, inflation is elevated. And second, upside risks to the inflation outlook are materialising. This implies that the RBA’s expectation (in August) of core inflation returning into the 2-3% target band in Q3 2027 is no longer the modal forecast. The Statement notes that upside inflation risks stem from a variety of sources, including elevated energy prices and the associated cost pass through to final prices, higher prices for tech-related goods and domestic capacity pressures.
As the policy rate reaches levels that are consistent with tighter financial conditions and a restrictive monetary policy setting, the focus of policy should – in theory – start to shift away from inflation and a little more towards growth. In this context, the commentary on activity data didn’t shift the tone to the Statement.
Indeed, the cyclical acceleration in global growth was a notable addition to this month’s Statement, relative to August. This is playing a decisive role, with commentary observing that “To date…growth in Australia’s major trading partners has been stronger than expected, as the boost from AI-related investment has outweighed the adverse effects of the Middle East conflict.” It speaks to the global nature of the tightening cycle underway, with the RBA joining the Fed, ECB, BoJ, RBNZ and Norges Bank in delivering a rate hike in September.
Domestically, the RBA notes that Q2 growth was stronger than expected at the margin and that business investment and credit growth remain robust. But even in parts of the economy where softer outcomes are evident (consumption and the labour market), the commentary doesn’t appear overly confident in the sustainability of any slowing. For example, the labour market is described as easing “…broadly as expected” while forward indicators of labour demand are described as “…broadly stable.”
The decline in dwelling prices and the associated slowing in mortgage lending are noted, with a concession that “…there are uncertainties about the economic effects of the downturn in the housing market.” In the press conference, the Governor went a little further, acknowledging that housing represented a downside risk to the outlook.
Effectively, putting additional hikes in the forecast is a call on whether the RBA’s reaction function has changed. Commentary from the Governor in the press conference suggests that the strategy of fine tuning has been retained for now, assuming inflation expectations remain well behaved. As such, it is possible that with financial conditions now tighter, officials will be content to watch for a while and only react if more bad news is received on the inflation front. The Governor noted the lags associated with monetary policy require the Monetary Policy Board to see how the 100bp of hikes delivered so far “feed through”.
It is important to note that with policy now considered restrictive (or close to) by the Monetary Policy Board, each decision to hike from here is – by definition – a tougher call. This is especially so if activity data are printing weaker than expected, as has been the case in the past week or so (household spending indicator, unemployment rate, PMIs). Moreover, our forecasts as they stand today – cash rate peaking at 4.6%, core inflation in the target band by end 2027 – will see the real cash rate at ~1% or higher for the next 12-18 months. This is not necessarily high by historical standards, but our judgement today is that it looks high enough for now for an economy that is already slowing.
For all media enquiries, please contact the NAB Media Line on +61 3 7035 5015